Pooled Group Benefits Plans: Stable Renewals, Not Necessarily Lower Costs
Pooled group benefits plans are often pitched to small businesses as the fix for unpredictable renewals — but the pitch usually only tells you half the story.
The logic is simple: instead of your company’s claims deciding your premium on their own, your employees get folded into a much bigger pool — thousands of other plan members across other companies. Risk gets spread around. Renewals feel calmer.
That part is true.
What usually goes unsaid is this: premium stability is not the same thing as cost control.
What Pooled Group Benefits Plans Actually Do
A pooled plan reduces how much your own claims history affects your renewal by blending it with a much larger group’s experience. That protects a small employer from one bad year wrecking their numbers.
It’s a real advantage, and it shouldn’t be dismissed.
But the trade-off is this: your own good claims experience stops working exclusively in your favour. If your employees barely claim while others in the pool claim heavily, part of your premium is quietly subsidizing those other companies. If it’s the other way around, you’re the one being subsidized — for now.
Pooling doesn’t make cost disappear. It redistributes it.
Where Pooled Group Benefits Plans Make Sense — and Where They Don’t
Pooling is the right tool when the risk being insured is rare, unpredictable, and financially serious. Life insurance, disability insurance, critical illness coverage, catastrophic drug costs — nobody knows who will need them, so spreading that risk across a large group is exactly how insurance is supposed to work.
Routine health and dental expenses are a different category entirely.
A cleaning, a pair of glasses, a massage, a physio visit — these aren’t catastrophic events. They’re predictable transactions employees can use, delay, or max out depending on what the plan allows. And once a benefit exists, people use it. That’s not a character flaw. That’s just incentives doing what incentives do.
How Pooled Group Benefits Plans Still Drive Renewals Up
Most small business plans are experience-rated in some form, even inside a pool. The insurer compares premiums collected to claims paid, adds its margin, and adjusts. If claims run ahead of what was priced in, the increase eventually lands on someone.
Here’s the uncomfortable part: the plan itself is what encourages the spending. The employer pays for access to a long menu of benefits, employees reasonably use what’s available, and then the renewal reflects that usage as if it were a surprise.
It isn’t a surprise. It’s the model working as designed — just not in the employer’s favour.
Pooled vs. Experience-Rated vs. Pay-Per-Claim
| Experience-Rated Plan | Pooled Plan | Pay-Per-Claim (Kibono) | |
|---|---|---|---|
| Renewal volatility | High — one bad year can spike it | Lower — smoothed across the pool | None — no renewal to negotiate |
| Who pays for others’ claims | Mostly your own group | Blended with the whole pool | Nobody — you fund only what your team uses |
| Cost if claims stay low | Rewarded next renewal | Partially absorbed into the pool | You simply spend less |
| Admin fees on unused capacity | Built into premium either way | Built into premium either way | Only on what’s actually claimed |
Claims Transparency: What to Ask Before Joining a Pooled Plan
Some pooled arrangements make it genuinely hard to get company-specific claims data. The explanation is usually that your individual experience “doesn’t drive the renewal” in a pool — which may be contractually true, but doesn’t make the numbers irrelevant to you.
Before signing on to a pooled plan, ask:
- What did we pay in premiums, and what was actually claimed on our behalf?
- Which categories are driving usage?
- How is the pool’s renewal increase calculated?
- Does a low-claiming group get any credit for that?
- What claims history will we be able to take with us if we leave?
If the pitch leans heavily on “the pool is strong and stable,” you should be able to see the data that backs that up — Ontario’s insurance regulator requires carriers to be transparent about how group plans are priced and administered.
A Better Structure Than a Pooled Group Benefits Plan
Insurance works best when it protects against losses people genuinely can’t absorb on their own — life, disability, critical illness, catastrophic drug costs. That part deserves real pooling, and Canada’s insurers already run industry-wide pooling arrangements for exactly that kind of catastrophic risk.
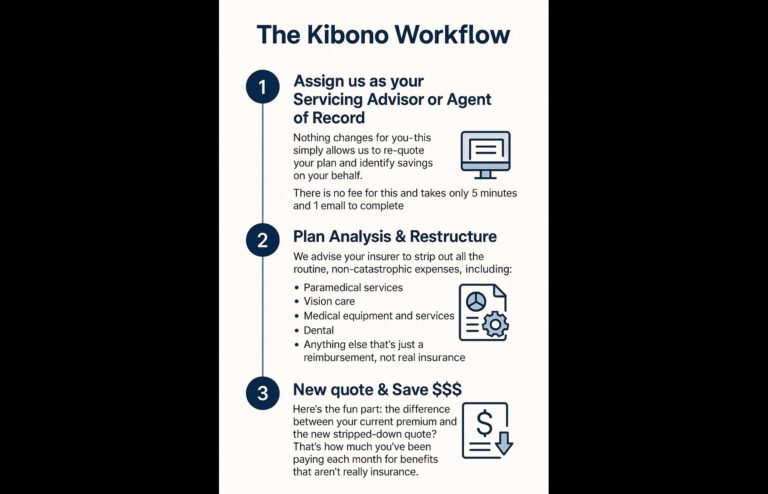
Routine dental, vision, and paramedical expenses don’t need to be insured at all. The CRA recognizes Health Spending Accounts as a legitimate, tax-free way to reimburse these costs — which is exactly what a Health Spending Account or a pay-per-claim model like Kibono is built for. You set the ceiling, employees use what they need, and you’re never funding pooled risk on expenses that were never really unpredictable in the first place.
A hybrid approach — catastrophic risks insured, routine spending funded directly — gives you the protection where it matters and removes the guesswork everywhere else.
The Bottom Line on Pooled Group Benefits Plans
Pooled group benefits plans solve a volatility problem. They smooth the curve so one bad year doesn’t wreck your renewal.
What they don’t solve is the underlying cost problem: routine, predictable expenses being priced and managed like insurance risk.
A bigger pool spreads the cost around. It doesn’t make it go away.
Want a Plan That Doesn’t Rely on a Pool at All?
Kibono is built around pay-per-claim pricing — no pooled risk, no renewal guesswork, no paying for coverage nobody used. You fund a budget, employees use it, and that’s the whole model.
Book a consultation to see what it looks like for your team, or read more about employee benefits in Canada.
Frequently Asked Questions
What is a pooled group benefits plan?
It’s a benefits plan where your employees’ claims are combined with a much larger group of members across many employers, so your individual claims history has less impact on your renewal.
Are pooled plans cheaper than traditional group insurance?
Not necessarily. They tend to produce steadier, more predictable renewals, but the total cost of the pool’s claims still has to be covered by premiums — a pool smooths volatility, it doesn’t reduce underlying spending.
What’s the alternative to a pooled group benefits plan?
A hybrid structure: insurance for genuinely catastrophic risks (life, disability, critical illness), paired with a Health Spending Account or pay-per-claim model for routine, predictable expenses like dental and vision.